Strategic Initiatives
12527 stories
·
45 followers

Two Asian giants, one economic trap

1 Share

LLM (google/gemini-3.8-flash) summary:

  • Consumer Sentiment: falling property values and high youth unemployment cause households to hoard cash and downgrade consumption
  • Property Market Collapse: real estate contraction triggers a balance sheet recession where citizens and firms focus on paying debt instead of spending
  • Demographic Contraction: population shrinkage began recently and threatens long term economic stability at a steeper rate than observed in japan
  • Credit Demand Weakness: government bond yields fall and lending growth hits record lows as borrowing appetite across sectors evaporates
  • Export Resilience: manufacturing capacity and record trade surpluses maintain global market share and cushion domestic downturns
  • Youth Unemployment: millions of young workers enter a stagnant job market creating a disillusioned generation reluctant to invest in housing
  • Fiscal Policy Hesitation: leaders avoid direct household stimulus to address weak consumption and focus resources on advanced technology instead
  • Economic Trajectory Revision: slowing annual growth diminishes previous forecasts of surpassing the united states as the leading global economy

Xu, a semiconductor engineer in Shanghai, should feel like a master of the universe in China’s new economy. He earns well in a sector critical to the nation’s future and lavished for decades with state subsidies. 
Yet for all the promise on his horizon, the 29-year-old is reluctant to splash his cash. His income, in an environment of high youth unemployment, falling property values and a threadbare social security net, feels more precious by the day. An atmosphere of consumer “downgrading” and pessimism, he says, is everywhere. 
“I am also under more pressure now,” Xu adds, “so I’m less inclined to go out and spend.”
Such an evaporation of confidence is chillingly familiar. To Xu and millions like him, the world’s second-biggest economy increasingly resembles that of Japan during the long period of stagnation and deflation that followed the bursting of its property bubble in 1990.
The parallels are everywhere, from deteriorating demographics, persistent deflation and weak consumer spending to moribund stock and property markets. At around 300 per cent of GDP, according to calculations by Capital Economics, China’s total public and private debt is also closing in on Japanese levels.
China
202520202015201020052000199519900105-515USUSEurozoneEurozoneJapanJapanChinaChina
China’s leaders have studied Japan’s experience in detail, in an effort to avoid the policy mistakes that bedevilled Tokyo’s response to the slump.
But despite their efforts, signs of Japan-style malaise, such as reluctant consumers and deflationary pressures, are still proliferating in China.
According to Goldman Sachs, an updated version of the Japanisation index — a gauge originally devised by the late economist Takatoshi Ito — shows that for the past five years, China has been consistently more “Japanised” than Japan itself. 
Looming over all of this is what economists describe as the iron law of demographics. Japan’s population started to shrink in 2009; China’s decline began in 2022 and is on track to be steeper, worsening the country’s economic prospects.
That outlook threatens President Xi Jinping’s reputation as a reliable steward of the economy, raising the prospect that the country will not surpass the US to become the world’s largest economy in the next one or two decades, as some once also believed Japan might.
In another echo of Japan’s post 1990s-slump, the IMF warned last week of growing numbers of “zombie” companies across Asia, kept alive only by lenient banks. This is now evident across China’s heavily subsidised manufacturing economy.
Outside favoured sectors, companies are increasingly refusing to invest while households hoard cash instead of spending. Phrases coined in 1990s Japan, such as “job hunting ice age” and “price destruction”, are creeping into China’s vernacular.
And while economists can see the signals of Japanification in the data, Xu can see it at breakfast, lunch and dinner. Restaurants across China are competing to offer meals for under Rmb10 ($1.50).
“The focus for customers seems to be on filling up, rather than the taste of the dishes themselves or the quality,” Xu says.
A young girl sits between her parents and eats a bowl of beef and rice using chopsticksThe price of a basic bowl of rice and beef at a leading gyudon chain in Japan fell after a peak in 1990, only recovering to the same level in 2021 © AFP/Getty ImagesA man sits in a restaurant and eats noodles using chopsticksRestaurants across China are competing to undercut each other’s prices to tempt increasingly cost-conscious diners © Wu Hao/EPA/Shutterstock
This too is redolent of Japan, where restaurants entered a margin-crushing price war to attract an ever-shrinking pool of consumer spending as deflation took hold. The price of a basic bowl of rice and beef at the nation’s leading gyudon chain hit a high of ¥400 ($2.50 at current exchange rates) at the end of 1990 before falling. It only reached ¥400 again in 2021.
“The criticism of Japan’s response was that it was too little, too late. It was slow to take the drastic measures that were required, and reluctant to take the pain,” says Toshiya Tsugami, a fellow at the Japan Institute of International Affairs think-tank who specialises in the comparison between the Chinese and Japanese economies. 
“China appears to be doing everything it can, but it is treating the symptoms only. In fact, China’s problems are getting bigger and more serious,” he adds. 
Although higher energy prices as a result of the Iran war have recently lifted Chinese factory-gate prices out of more than three years of deflation, economists say weak demand continues to fester. Consumers are deleveraging, with bank lending to households as of August this year declining outright for the first time in history.
Five years on from the bursting of China’s property bubble, some economists are concerned over whether the economy is now halfway through its first “lost decade” — and whether that could extend into a second or even a third. 
But others counter that the two economies are very different. Andrew Tilton, chief Asia-Pacific economist at Goldman Sachs, says that China “has been at pains to make sure its manufacturing sector stays competitive and maintains market share”. Third-quarter year-on-year GDP growth of 4.5 per cent, announced this week, was driven substantially by export growth.
China is also less developed now than Japan was when its bubble burst, leaving more room for growth, and it is more able to resist political pressure from the US over exchange rates than Japan was.
2040
204020352030202520202015201020052000010080604020
Isabelle Mateos y Lago, chief economist at BNP Paribas, says that while there are parallels, these differences seem far more important. “China could reflate its domestic economy by addressing the root causes of households’ astonishingly high savings rate, which is roughly twice Japan’s in the early 1980s,” she says.
Even so, the reversal in sentiment from a decade ago is striking. “It isn’t so long ago since people were drawing lines on charts that showed China keeping on growing at 7, 8 or even 10 per cent [a year] for another couple of decades,” says Adam Slater, lead economist at Oxford Economics.
“Now all of a sudden we’re looking at, within a decade, Chinese growth dropping towards 3 per cent per year. It’s a very big change in the outlook.”

China’s real estate bubble was the largest in history, outpacing even Japan’s speculative frenzy of the late 1980s and at its peak accounting for a third of the country’s economy.
The contraction since it burst in 2021 has been dramatic, with new housing starts down 78 per cent from their peak, according to Macquarie. That compares with a 73 per cent fall in the US between 2005 and 2009 and Japan’s 65 per cent drop between 1996 and 2025. 
The collapse of the property market has set off what Richard Koo, the Nomura Research Institute’s chief economist, calls a “balance sheet recession” — a term he originally coined in the 1990s to describe the tendency of Japanese companies and individuals to pay down debt rather than borrow to invest or spend.
Weaker demand and deflation then worsen the debt burden, leading to a vicious cycle. Investment opportunities decline, the labour market calcifies and salaries stagnate.
Tokyo station packed with commutersCommuters in Tokyo in 1990, the year Japan’s property bubble burst, leading to a long period of stagnation and deflation © The Asahi Shimbun/Getty ImagesSchoolchildren and commuters riding bicycles and electric mopeds wait at a traffic light in BeijingChina’s demographic decline began in 2022 and is on track to be steeper than Japan’s, worsening the country’s economic prospects © Andres Martinez Casares/EPA/Shutterstock
Just as it did in Japan, demand for debt has slowed markedly in China since the real estate bust. The country’s total outstanding renminbi-denominated loans rose 4.8 per cent in September from a year earlier, a record low, and down from 4.9 per cent in August. 
China’s weakening economic conditions meant that up to 10.6 per cent of the adult population had overdue loans last year, compared with about 7.8 per cent a year earlier, according to a report by Gavekal Dragonomics analyst Xiaoxi Zhang.
China’s official statistics show an uncannily stable urban unemployment rate of about 5 per cent. But youth unemployment is high by international standards at 18.9 per cent in August. 
The country’s local governments are also trying to reduce debt after borrowing hundreds of billions of dollars to finance often unproductive investments during the property boom.
The province of Guizhou alone binged about Rmb770bn ($115bn) a year on large infrastructure projects between 2017 and 2023, including some of the world’s highest bridges. Now that high-spending era appears to be over.
In the private sector, companies in favoured high-tech sectors or export industries are still borrowing, but those exposed to the weak domestic economy are not.
The ultimate sign of China’s weak credit demand is the 1.7 per cent yield on 10-year government bonds, which Nomura’s Koo describes as “absolutely ridiculous”. Prices, which move inversely to yields, have risen because investors are unpersuaded by the opportunities on offer elsewhere in the country and have parked cash in government debt. The yield “should be 3 or 4 per cent at a minimum”, adds Koo.
He argues that the best response to a balance-sheet recession is increased fiscal spending by government to mobilise the savings accrued in the banking system, rather than repeating Japan’s mistake of using lower interest rates to stimulate the economy. Loose monetary policy merely encouraged companies to limp along without addressing fundamental flaws in their business models and resulted in capital misallocation, he adds.
Xi’s administration has announced some spending programmes for consumption, such as subsidies for one-off purchases of consumer goods, including televisions and appliances. But these have only brought forward spending by households rather than raising incomes. 
“A lot of people in China fully understand the need for fiscal stimulus but the government is still not adapting [its] stance fully,” says Koo. “It has done some, but nothing near enough to offset the deflationary pressure.”

One reason for Beijing’s reluctance to resort to domestic stimulus, economists believe, is China’s strong export performance. The trade surplus hit $1.2tn last year — the biggest recorded by any country, ever — and may meet or exceed that level this year.
Policymakers in Beijing think the country’s export performance will buy China time while it waits for the property market to stabilise. In the meantime, they are pursuing investment in areas such as chipmaking and AI as the country competes with the US for geopolitical dominance.
One Chinese government adviser, speaking on condition of anonymity, says the top leadership believes that its long-term investment in high-tech will bring a pay-off that was not seen after the bubble burst in Japan.
The adviser points to China’s growing capabilities in semiconductor manufacturing, an industry where Japan ceded ground to Taiwan and South Korea during its two lost decades.  
2050
All series are visible.
China
Japan (1973-2023)
S Korea (1973-2023)
Taiwan (1973-2023)
20502045204020352030202520202015201020052000010080604020160140120
“So China is different. China did this on purpose,” the adviser adds. “We did not wait until the [property] bubble burst itself — we intentionally, we proactively made this happen.”
He says Beijing is making sacrifices now, in terms of weak domestic sentiment, in exchange for the long-term benefits. “They believe that this [the property downturn] will not last very long.”
Japan’s share of global manufacturing value was 23 per cent in 1995, falling to 11 per cent in 2010. China’s share was still 28 per cent in 2024. Some economists note that since the country’s property bubble burst, China’s exporters have increased their share of global manufacturing while Japan’s fell. 
“Since the onset of US-China trade tensions in 2018, China’s overall exports have risen about 52 per cent, and its goods surplus has more than tripled,” said Larry Hu, chief China economist at Macquarie, in a research note. 
He said that contrasted sharply with Japan, where corporate capital expenditure declined by about 14 per cent from 1990 to 2010 as companies repaired their balance sheets. “That persistent capex weakness helps explain why Japan missed much of the subsequent waves of technological change in the internet and semiconductors.”
 Workers assemble on the production line at the Toyota in Japan in 1997A Toyota assembly line in Japan in 1997. The country’s share of global manufacturing value was 23% in 1995, falling to 11 per cent in 2010 © The Asahi Shimbun/Getty ImagesWorkers assemble a power-generation unit for a wind turbine in China in 2026Assembly of a wind power generation unit in China, where the share of global manufacturing — 28% in 2024 — has increased since the property bubble burst in 2021 © Qilai Shen/Bloomberg
Others caution that China’s manufacturing export boom may yet prove unsustainable as big trade partners such as the US and EU push back more forcefully against the flood of cheap exports.
In 1985, when Japan’s exports were booming, it was in effect forced to rebalance its economy by allowing the yen to appreciate. The so-called Plaza Accord with the US and others kept Japan’s trading partners open to receiving its goods, Koo argued. 
But Chinese propaganda portrays the agreement as a capitulation. “Japan’s acquiescence was influenced as much by its security dependence on the US as by economic factors, and the resulting shock triggered Japan’s asset collapse and prolonged economic stagnation,” said the official China Daily newspaper last month.
“Japan was responsive to US political and policy pressure [over its weak currency] in a way China is not,” says Tilton, at Goldman Sachs. “Without the same electoral constraints, China can continue directing resources away from the household sector for longer than Japan could.”
Macquarie’s Hu argues that even if exports prove unsustainable at their current levels, Beijing still has enough fiscal firepower to stimulate consumption. 
“After five years of painful adjustments, policymakers have deflated the property bubble,” he wrote. “Now, with low inflation, low rates, and an undervalued currency, they have ample policy space to pivot, such as [through] rolling out forceful housing stimulus.”

Not everyone is convinced such a shift will be easy. Just as two generations of Japanese endured the fallout from the collapse of the 1980s bubble, a generation of young Chinese people is now bearing the brunt of their country’s domestic slowdown.
Gavekal analyst Andrew Batson calculates that about 74mn Chinese have completed their education and entered the workforce since 2022.
2060
All series are visible.
0-14
15-59
60+
China0604020Japan2060205020402030202020102000199019501960198019700604020ForecastForecastForecastForecast
The weak economy means many members of this “lost generation” will become disillusioned with their prospects, he argues, making it more difficult to stabilise the property market.
This psychological cloud, argue Goldman Sachs analysts, matters even more than the demographic overhang in judging how hard Japanification might hit China.
The “expectation channel”, where households and businesses saw no prospect of longer-term growth, created a vicious circle of reduced consumption and investment in Japan which in turn lowered expectations.
Zhu Ning, an economist and author of a book about China’s property bubble, says younger people “just don’t think buying a property makes economic sense or investment sense, because all [they] have experienced is that housing prices came down 30 to 40 per cent in a matter of five years.”
The stock market could offer a substitute for some households looking for investment opportunities, he adds, with about 200mn Chinese holding some shares.  
But for some economists, a bigger question is whether China’s bubble has actually fully burst, given the country’s still extraordinarily high investment rates.
Gross fixed capital formation — the acquisition of assets for the production of goods and services — was 40 per cent of GDP in 2024 against Japan’s 28 per cent and the OECD average of 22 per cent, fuelled by an augmented fiscal deficit that Goldman Sachs forecasts will hit 11 per cent of GDP this year. No one knows when this debt will become unsustainable. 
Investors watch a board displaying stock prices in Tokyo in 1990Investors watch plunging share prices in Tokyo in 1990. Reduced consumption and investment in Japan have created a vicious circle of low expectations © The Asahi Shimbun/Getty ImagesWorkers labour at the construction site of a residential building in ChinaPolicymakers say export performance will buy China time for the property market to stabilise, but analysts think a disillusioned ‘lost generation’ will make this more difficult © FeatureChina/AP
“I would say China hasn’t really started its adjustment yet because debt continues to rise at an astonishingly rapid pace,” says Michael Pettis, a senior fellow at the Carnegie Endowment for International Peace. “We’re going to see a surge in investment growth later on this year, because I don’t think [China’s leaders] are prepared to see GDP growth come in below target at 4 per cent.”
In Japan’s case, the adjustment started relatively clearly in 1991 after the collapse of the real estate and stock markets. “I’m not sure we’re going to have such a clean starting date with China,” adds Pettis. 
Some might say China’s adjustment began in 2022 after the crackdown on housing sector over-leverage, or even as far back as 2015 when a stock market collapse led the country to cut interest rates, setting off the last phase of the housing boom. More recently, there has been a boom in manufacturing. 
The seminal book Japan as Number One, published in 1979, triggered a wave of predictions that the Japanese economy would overtake that of the US. Such forecasts endured even after Japan had entered its first lost decade.
Similar pronouncements regarding China, which proliferated until recently, have become more scarce. If Beijing cannot shake off Japanification, the prospect of convergence with the US will fade.
Slater, at Oxford Economics, does not rule out the possibility that the country’s growth slows to between 2 and 2.5 per cent over the next decade — half the average of the last. In that case, Xi’s hope of overtaking the US might look increasingly forlorn, just as the challenge posed by Japan receded in the 1990s.
“The catch-up process would pretty much level off,” he says.
Data visualisation by Keith Fray
Read the whole story
bogorad
3 hours ago
reply
Barcelona, Catalonia, Spain
Share this story
Delete

Some final words on Foursquare. - by Dennis Crowley

1 Share

LLM (minimax/minimax-m3.1-flash:free) summary:

  • Acquisition: foursquare was acquired by infillion after a seventeen year history
  • Equity Outcome: preferred and common shares were cancelled without payment, leaving equity holders with zero dollars
  • Revenue History: foursquare reported revenue above one hundred million dollars from twenty nineteen through twenty twenty one
  • Leadership Change: a private equity investment in twenty nineteen was followed by the deal banker becoming chief executive officer
  • Accountability: founder dens crowley accepted responsibility for earlier fundraising and board decisions while criticizing later leadership
  • Employee Communication: current and former employees learned of the zero dollar outcome through legal emails and a lengthy document
  • Company Legacy: foursquare influenced consumer location products, enterprise tools, employee careers, and new companies
  • Final Advice: founders should devote themselves to their companies while also accepting closure and pursuing new opportunities

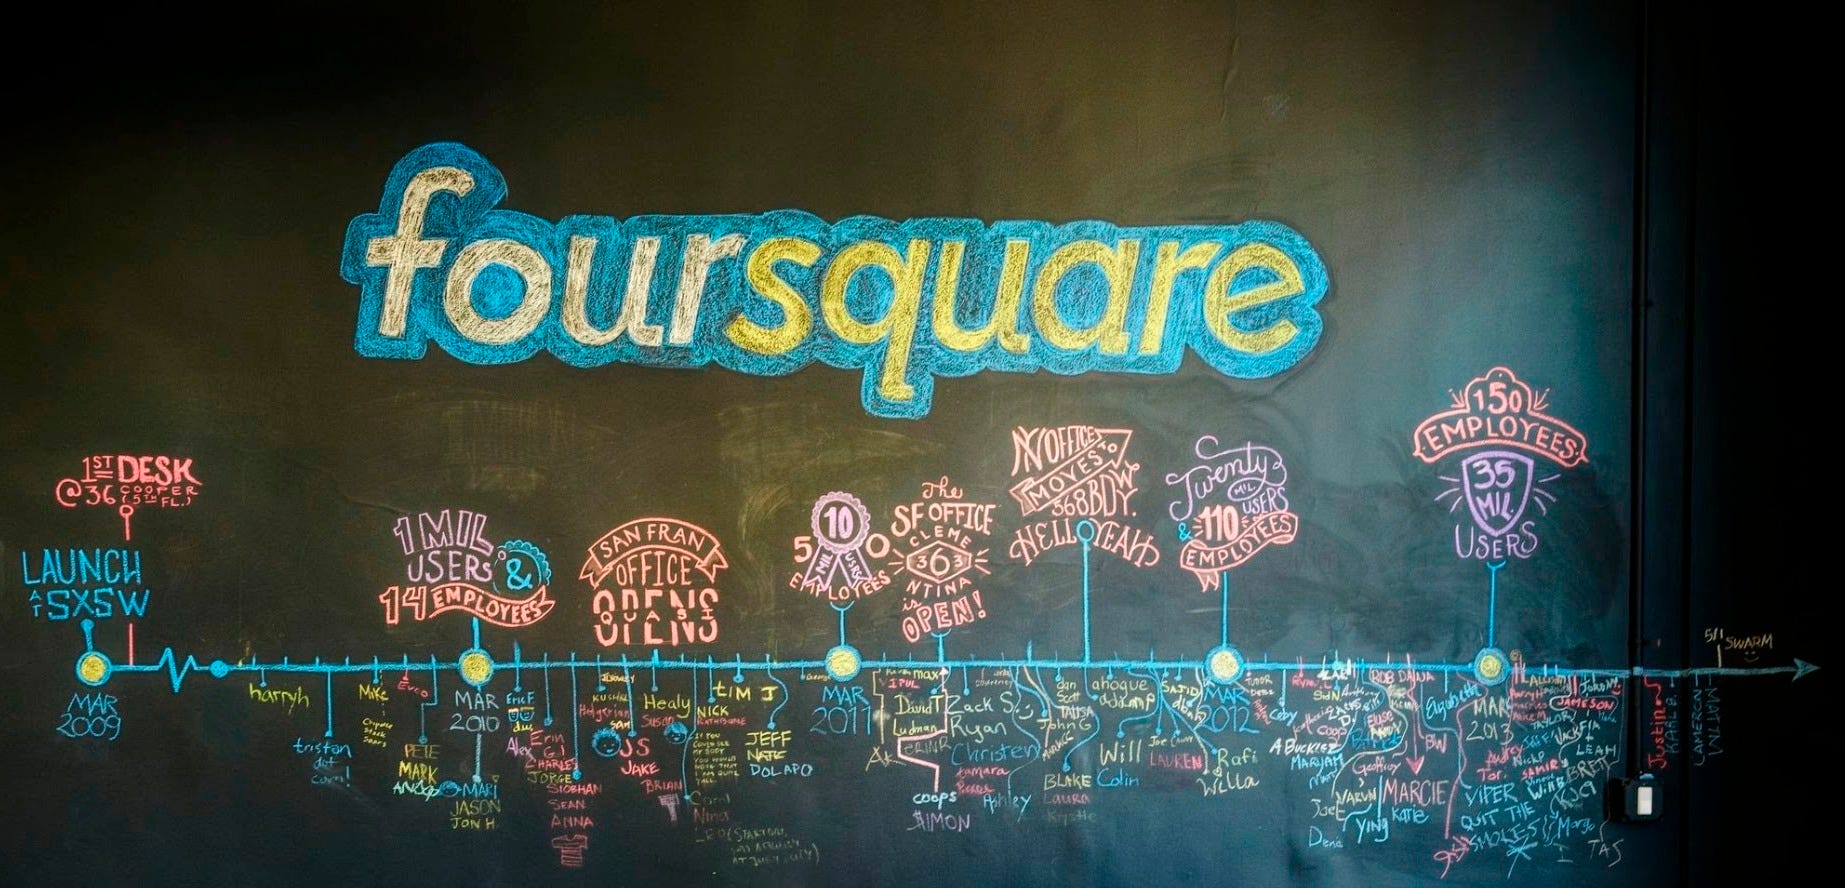
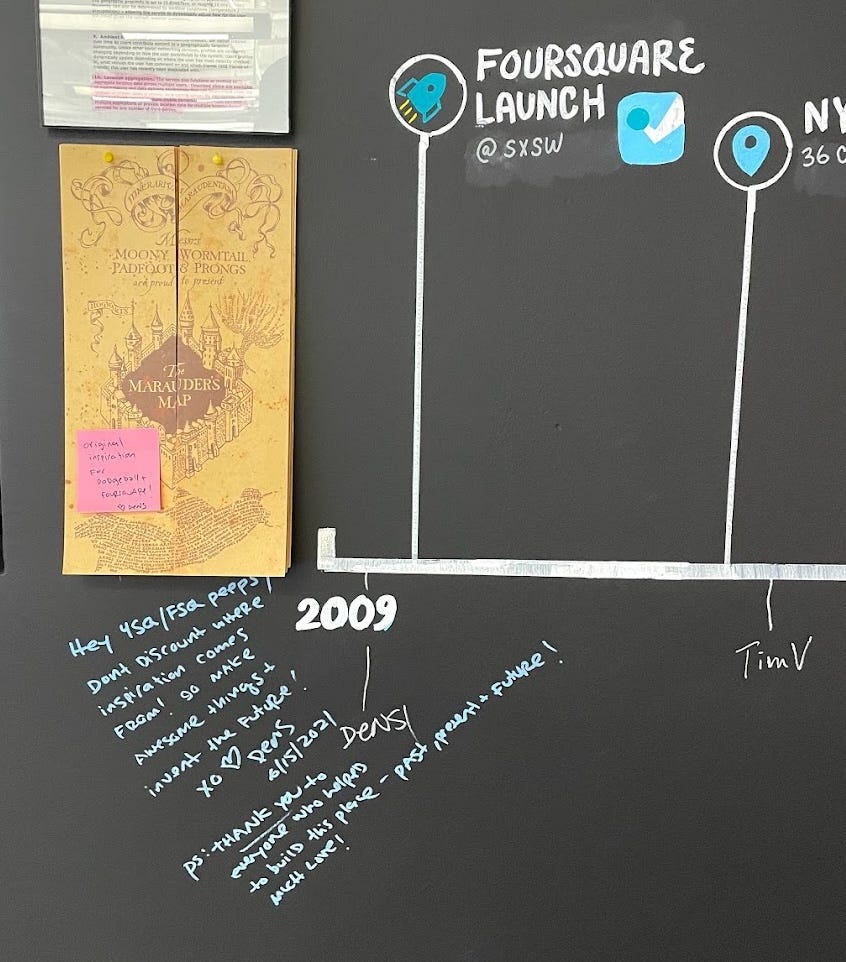
Timeline 1.0 (568 Broadway, NYC) – This timeline was a big deal at FSQ. Everyone added their own names and when they started, alongside company milestones & achievements.

Almost exactly a month ago, Foursquare was acquired, marking the end of a 17-year story that started around my kitchen table in the East Village in 2009. “The terms of the deal were not disclosed”, but some details have surfaced online. One of our earliest angel investors wrote…

>> Several days after the announcement I got the paperwork about the sale from Foursquare’s legal counsel. [...] around page 50 was the sentence I needed to see, which said that “each share of Preferred Stock was cancelled and extinguished, without any conversion thereof or payment of any cash or other property or consideration therefor, and ceased to exist.”

Translation: The Foursquare acquisition was a $0 outcome for equity holders – $0 for preferred, $0 for common. It’s bittersweet to see these details surface publicly – at least now there’s an opportunity to comment on them.

I was heartbroken by this ending. There are so many people who put so much time and energy and passion and love into building Foursquare – the company, the products, the brand, the culture. If you were part of it (or even close to it), you know exactly what I’m talking about. To our ~1600 former employees over 17 years, I am sorry the Foursquare story ended in such a way that makes it seem like our collective efforts were worth… nothing?

I’m writing this post for three reasons, (1) I want an artifact that that captures FSQ’s ending from my POV to exist on the internet, (2) I want to hold leadership (myself included) accountable for the outcome, and (3) I’ve learned a lot – strategically, emotionally, psychologically – about starting, scaling, and losing a company that I loved, and those learnings feel worthy of sharing with other founders and investors. “Trust” and “transparency” have always been core to Foursquare’s DNA, so if there’s going to be any last word on the company, they should echo these values.

I don’t think anyone was expecting a huge exit these days (there was a big capital stack to pay back before common saw anything, plus many people’s vested options and RSUs had expired), but seeing it go to zero is hard to accept.

Foursquare did struggle as we made the transition from a consumer business to an enterprise business… but we did it! In 2019, 2020 and 2021 we publicly boasted about our $100M+ revenue years. So what happened? In 2019, Foursquare raised additional capital from a private equity firm – the business was starting to work, we had just acquired Placed – and 19 months later the banker who led the capital raise was elevated to the role of Foursquare’s CEO. (Jan 2021)

And six years after that leadership change, we now know how the story ends – as a zero dollar outcome for equity holders. Leadership was unable to preserve the value it inherited or create new value during those six years. Over the past few weeks, dozens of current and former Foursquare employees have reached out to me to express their frustration with the leadership that led the company to this outcome. You can read plenty of the criticism on Glassdoor if you’re interested. There’s 40 pages of it.

I’ll take accountability too. I was the CEO for the first 7 years (and I raised both equity and debt) and was Chair/Co-Chair of the Board for 17 years (as the company raised *more* equity and debt), so I take responsibility in part for how we got here. We raised a lot of capital under my leadership, and my decisions as CEO led us to the point where we needed additional capital, including the private equity round in 2019. (I stepped out of the CEO role in 2016 and stepped away from my day-to-day role running the R&D Lab in 2021). I kept my Board Seat after I left and often thought of myself as a champion for the common shareholder. In hindsight, I could have pushed harder as a board member (though tricky when when holding just one of seven seats).

The CEO job is impossibly hard and often thankless, but even in the darkest of scenarios there’s a way to lead with grace and humility. To many current and former employees, the final chapter of the company felt disrespectful. To provide a single example, current employees told me that, despite an in-person all hands meeting, they learned their shares would be worth nothing via an email from Foursquare’s legal team. Former employees learned these details via an email from Carta, with details buried in a 125-page PDF sent from Foursquare’s legal team. No single individual stood up to own (or even acknowledge) the outcome – the antithesis of the transparency and trust that was so core to our early DNA.

From everything I’ve heard, leadership took no accountability and displayed little awareness of the role it played in how we got here. With any other ending (even one that didn’t clear the capital stack) this might have been a different blog post. Instead our final chapters seemed so hastily managed and handled with such little care that I was left to write this makeshift eulogy. You all deserved better.

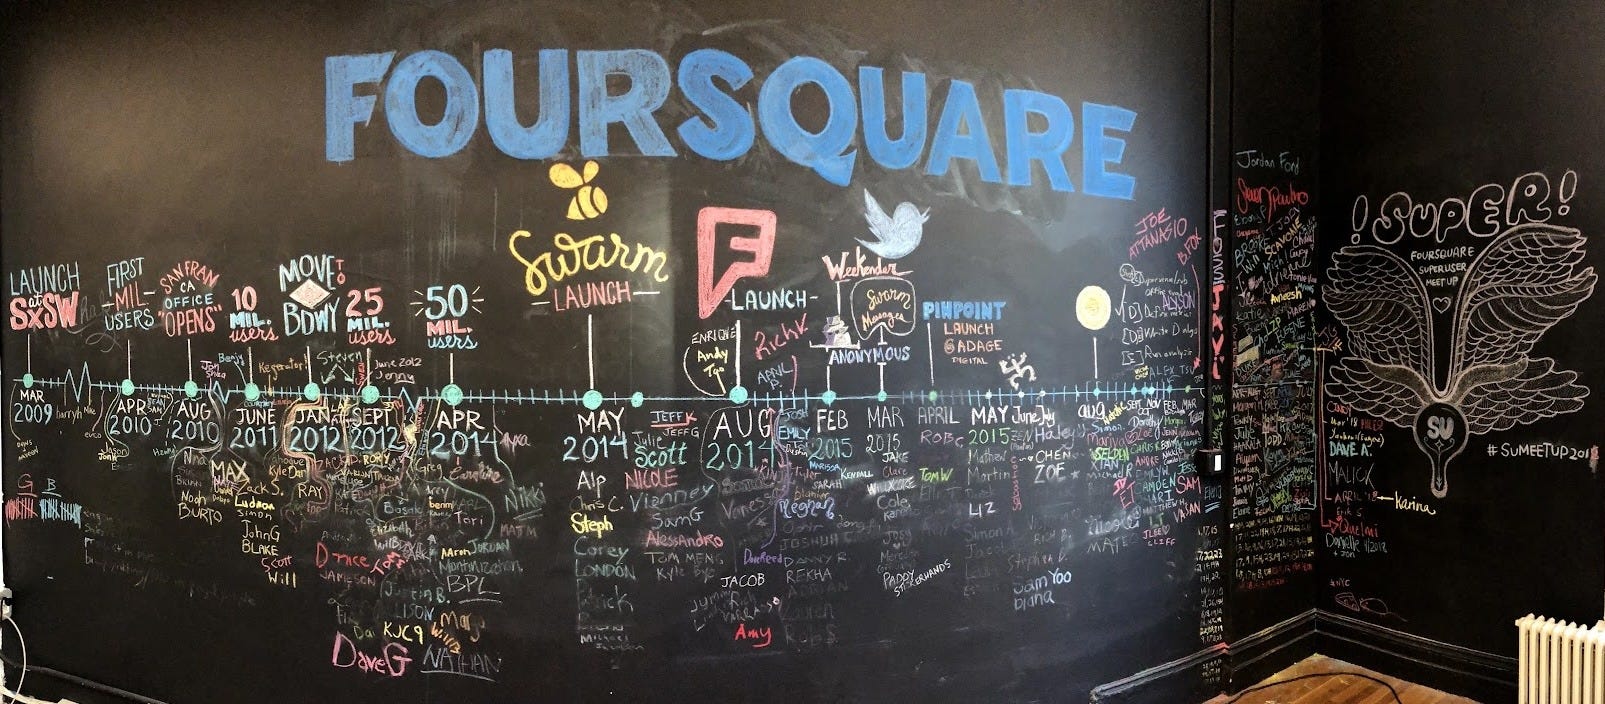
Timeline 2.0 (568 Broadway) – I took this photo the day we moved out of Soho HQ en route to Flatiron.
Zoomed in on the corner of the pic above.

ADVICE TO FOUNDERS / FINAL WORDS

<deep breath>

Maybe the biggest mistake I’ve made in my career is falling in love with this company**. I put my heart and soul into building it, and tried my best to keep the fire inside of it lit for the better part of 13 years. Looking back, I was far too loyal to the company and the idea of “making it work”. I stayed longer than I should have. I stayed believing that I was helping even though the people in charge didn’t want my help. Watching the company slowly decay has been a grind on my soul. The closure of it “being over” is helpful and welcome and cathartic. I don’t regret any of my time at Foursquare, though I do regret never letting myself “move on” from it (which has certainly held me back from exploring other paths over the years).

It was an ABSOLUTE HONOR to build this company with so many talented people back in the day. My north star for Foursquare’s culture (2010s) was always, “We want people to look back and think, ‘That was the best job I ever had because those were the best people I ever worked with’.” And I hear from ex-Foursquare people over and over again that we absolutely nailed this.

Regardless of this ending, I will always be SO PROUD of the amazing team, company and culture that we created together — one that allowed us to build consumer products that meant so much to millions of people (and inspired features you can now find in everything from Google Maps to Snapchat), and enterprise products that set the bar for how smaller teams could innovate and compete against the biggest of players. Watching hundreds of ex-FSQ people supporting each other in our alumni chat, hiring old teammates as they move from gig to gig, and starting companies (or families!) together never gets old. In my mind, your successes are part of FSQ’s legacy.

I will always be SO THANKFUL for the journey FSQ took me on and how the company got to influence so many people’s careers and stories. Foursquare played a defining role in the grand story that is NYC Tech, and the startup ecosystem that thrives here today will always be a core part of that FSQ legacy. I’m thankful for the investors who took a chance on us, and the army of friends and fans who supported us along the way. I just wish we all got to share a better ending together – an ending worthy of the same energy, passion and conviction that fueled the best parts of Foursquare’s story.

** I imagine I’m gonna get dragged for this “falling in love with the company” thing. If you have never experienced this, I *think* I’d recommend it? Building something you love, with people you love working with, for people who love the things you build for them is one of the BEST things I have ever experienced (and anyone who worked at FSQ in the earlier days will know this feeling) To anyone building, It’s okay to fall in love with the company you’re building, but don’t deny yourself the ability to get closure and move on just because the company itself hasn’t yet experienced an exit or ending.

ps: If you’re looking for a proper eulogy for the company’s achievements and legacy, read this. I wrote it six years ago, but it still holds up. Steven Rosenblatt (FSQ’s OG CRO) also wrote a great post-mortem.


I published this here because LinkedIn felt too… self-congratulatory for this post.
I’ll eventually cross-post to Medium for archival purposes.
Love and appreciation to anyone who read this far. 👋❤️
</end>

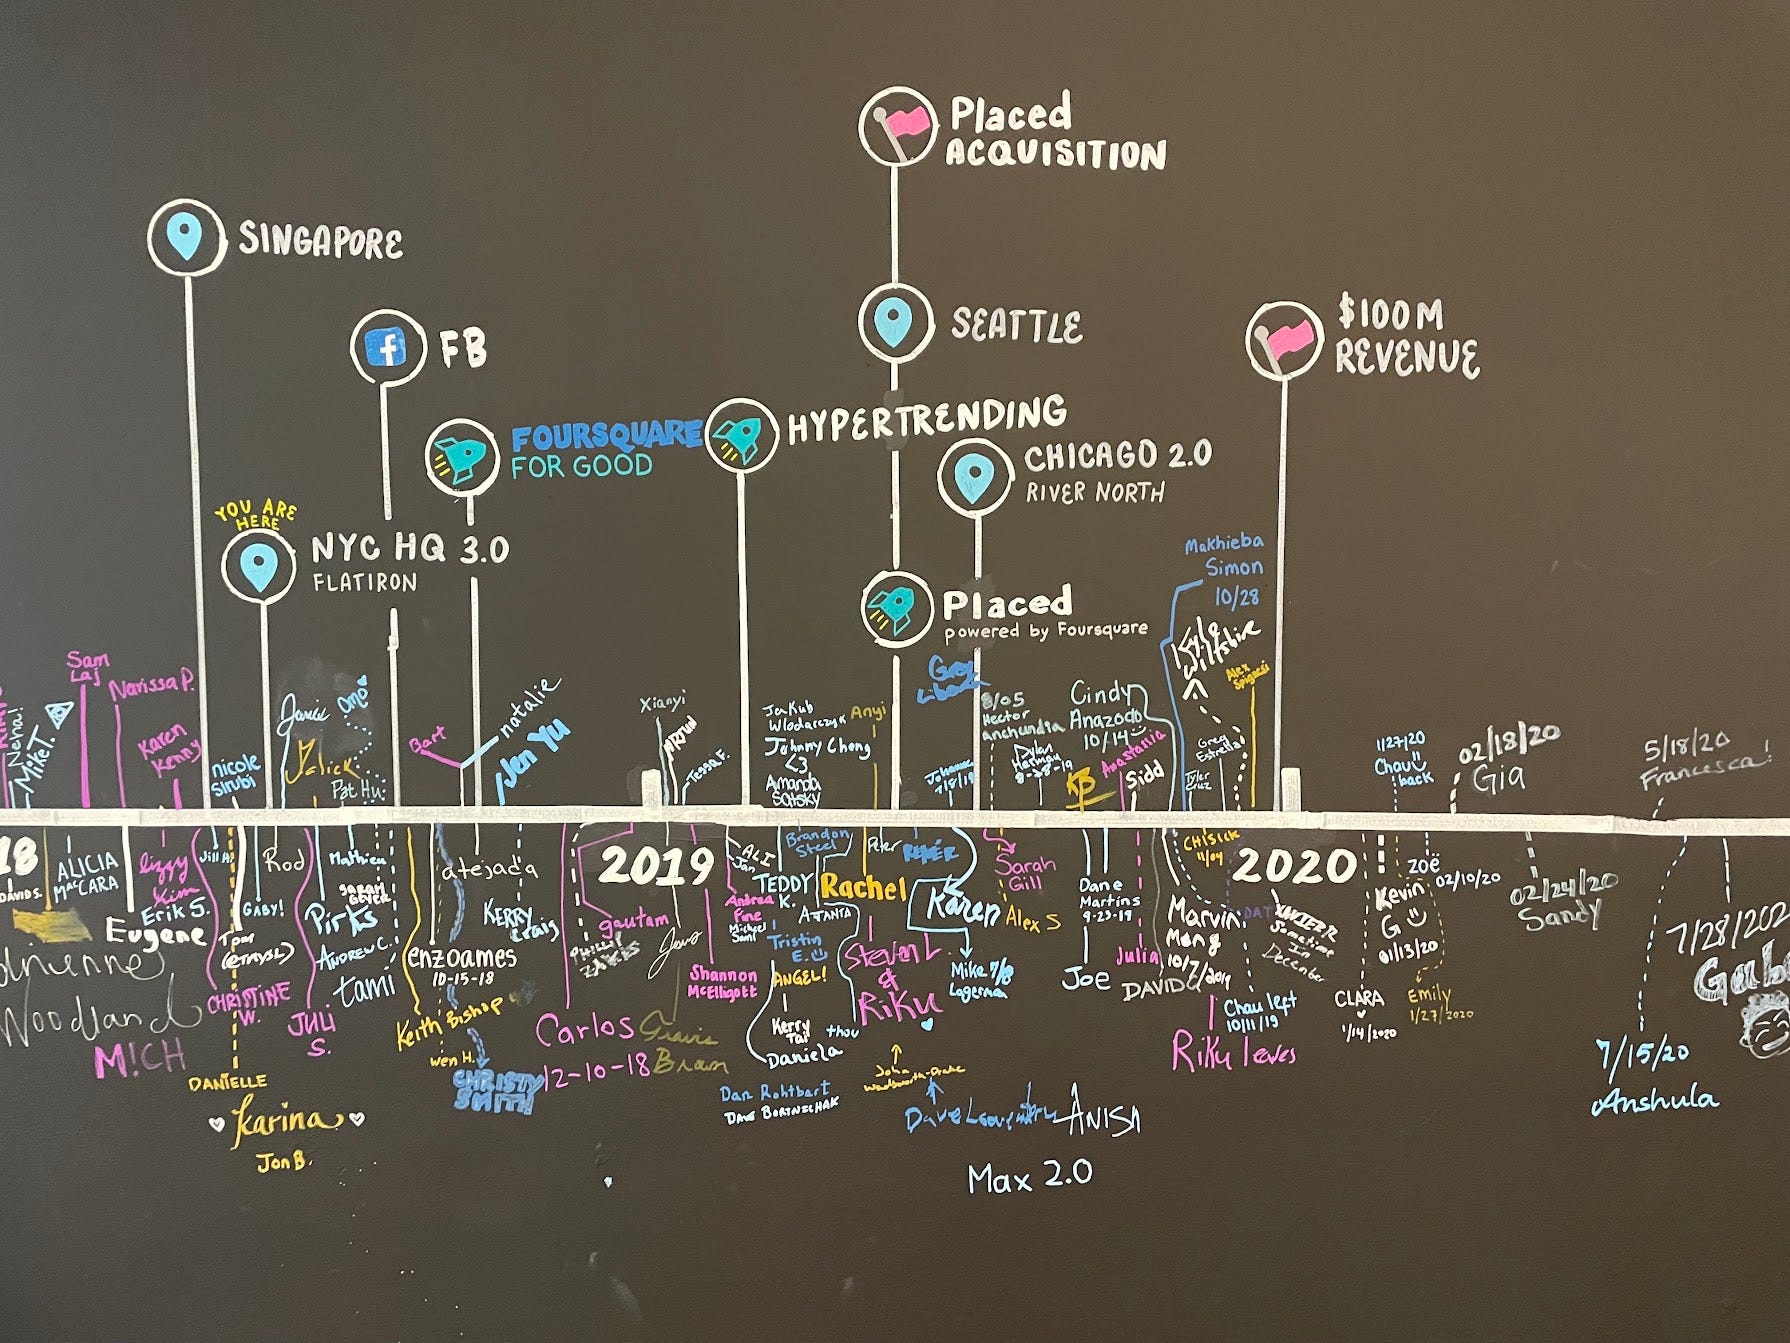
Timeline 3.0 (50 West 23rd Street) … before leadership erased it (!!) in late 2023. 🤦🏻‍♂️ This timeline stretched some 50 feet (and at least 13 years)
I left this note on my last day: “Hey 4SQ/FSQ peeps – Don’t discount where inspiration comes from! Go make awesome things + invent the future! xo, dens ps: THANK YOU to everyone who helped build this place – past, present & future! Much love!” – June 15, 2021 (a lifetime ago!)

Thanks for reading Teendrama Snippets! I try to write something 1-2x/month.

Read the whole story
bogorad
1 day ago
reply
Barcelona, Catalonia, Spain
Share this story
Delete

How Trump defied the 'experts' — and pushed the UN to post-Oct. 7 peace

1 Share

LLM (meta/muse-spark-1.3-contributor) summary:

  • October Seven Attacks: hamas murdered twelve hundred innocents and took two hundred fifty one hostages to gaza
  • Hostages Home: all two hundred fifty one hostages are home and ceasefire has held
  • Abraham Accords Expansion: accords survived war with iran and continue expanding with regional partners
  • Iran Axis Collapse: hamas and iranian backers failed as lebanon syria and iraq turn westward
  • United Nations Failure: leaders used equivocation and failed to rein in special rapporteurs
  • Rapporteurs And Unrwa: rapporteurs rationalized attacks denied rape while unrwa staff participated in horrors
  • Trump Gaza Proposal: bring hostages home demilitarize gaza and form technocratic administration with partners
  • Resolution Twentyeight Zero Three: endorsed plan welcomed board of peace with twenty eight members and authorized stabilization force with seventeen billion pledged

Pure evil.

There were no other words I could conjure on Oct. 7, 2023, when Hamas terrorists murdered 1,200 innocents, raped an untold number, ravaged entire villages in southern Israel and took 251 hostages back to Gaza — including American citizens, women, children and the elderly.

Three years later, the terrorists and their Iranian patrons have definitively failed.

The hostages are home.

The Abraham Accords are accelerating.

Regional partners are helping shape Gaza’s future.

And thanks to President Donald Trump, the same United Natons that was part of the problem in 2023 now has an opportunity — indeed, a mandate — to be part of the solution.

The UN’s moral inversion in the wake of Oct. 7 was surreal.

Senior leaders trafficked in caveats, equivocation, legitimization and delay — all while failing to rein in the special rapporteurs whose “independent expertise” they routinely invoke.

Take Francesca Albanese, the UN special rapporteur on the occupied Palestinan territories who rationalized Oct. 7 as a response to Israeli “oppression” — then used her UN role to target American companies like Microsoft, Caterpillar and Palantir for doing business in Israel.

Or consider Reem Alsalem, the rapporteur charged with combating violence against women, who denied that rape even occurred during the Hamas onslaught.

Special Rapporteur Tlaleng Mofokeng, ostensibly focused on health, declared that “Hamas are not terrorists” and defended the legitimacy of its “armed struggle,” while other rapporteurs led demands for arms embargoes, economic blockades and sanctions against Israel.

All this after employees from UNRWA (the UN agency entrusted with aiding Palestinians) participated in the horrors of Oct. 7.

This was the moral absurdity: While innocent hostages from Israel and roughly 25 other UN member states were still being starved and beaten underground in Gaza, parts of the institution founded to promote peace and human rights were parroting Hamas’ talking points and denying the nature of the atrocities.

They falsely attacked Israel and its partners, and confidently predicted that the regional peace architecture President Trump had built would collapse.

The world’s “experts” were wrong about all of it.

They were poor historians, but even worse prophets: The Abraham Accords survived Oct. 7, the Gaza war and the conflict with Iran.

Better yet, they are still expanding.

Hamas and its Iranian backers were wrong, too.

The Oct. 7 attacks were meant to fracture Israel from the region and breathe new life into Tehran’s Axis of Terror.

They backfired spectacularly: New governments in Lebanon, Syria and Iraq are casting off the Iranian yoke and turning Westward, and Iran’s “Axis of Resistance” is in shambles.

Just this summer I visited various allies in the Gulf.

At the height of the conflict with Iran, I sat in a restaurant in Abu Dhabi and heard Hebrew from diners at nearby tables — while Israeli Iron Dome batteries and personnel were helping defend Emirati skies from Iranian missiles.

A generation ago, that scene would have been impossible.

The same might be said of our efforts here at the UN, where we just convened members of the Abraham Accords for their first reunion since the first Trump administration.

The next day we hosted a ministerial summit between Morocco and Israel, where the two nations agreed to expand direct flights, elevate their diplomatic missions to embassies and move forward on new investment and tax agreements.

Those once-unlikely regional partnerships have given us a way forward in Gaza, where it once seemed there were only two options — Hamas could rule Gaza and continue its terror, or the IDF could stay in Gaza indefinitely.

President Trump put forward a third option: bring the hostages home, keep Hamas out of government, demilitarize Gaza, establish a technocratic Palestinian administration and bring Arab and international partners along for security and reconstruction.

We took that to the United Nations, where Security Council Resolution 2803 passed without opposition.

It endorsed the president’s plan, welcomed the Board of Peace and authorized an International Stabilization Force to secure Gaza, support vetted Palestinian police, protect civilians and humanitarian operations and prevent terrorist infrastructure from being rebuilt.

The results are now measurable.

All 251 hostages are home, and the cease-fire, while tenuous, has held.

The Board of Peace has 28 member countries, the ISF has completed its pre-deployment assessment and $17 billion has been pledged for reconstruction.

Much work remains, including the full decommissioning of Hamas and other armed groups — but there is now a framework where none existed before.

Oct. 7 was meant to destroy the possibility of a different Middle East.

Many within the UN accepted that premise; some even propagated it — staining the good work that can be done under its auspices.

In the 1,096 days that followed, President Trump has proved those voices wrong at every turn, corralling even naysaying institutions like the UN to advance what was once thought impossible in the Middle East: peace.

Mike Waltz is the US ambassador to the United Nations.

Read the whole story
bogorad
1 day ago
reply
Barcelona, Catalonia, Spain
Share this story
Delete

DHS Orders Federal Civilian Agencies to Remove China’s DeepSeek AI - WSJ

1 Share

LLM (minimax/minimax-m3.1-flash:free) summary:

  • Federal Removal Order: dhs ordered federal civilian agencies to remove chinese artificial intelligence technology developed by deepseek from their information technology systems
  • Future Purchases Barred: the order prohibits federal civilian agencies from buying deepseek products and services
  • Broad Product Scope: restrictions cover products developed by deepseek affiliates and third party products and services using deepseek implementations
  • China Related Technology: the ban applies to technology originating from a chinese artificial intelligence company
  • Legal Authority: dhs issued the order under the federal acquisition supply chain security act of 2018
  • Security Review: the decision followed a review of a recommendation and supporting evidence from the federal acquisition security council
  • Unspecified Rationale: the notice did not explain the security concerns underlying the restrictions or set a deadline for removing affected technology
  • Competitive Context: the action comes amid intensifying united states and china competition as chinese developers narrow the artificial intelligence capability gap to about two months


Illustration of the DeepSeek logo on a blue backlit keyboard.The restrictions extend to products developed by DeepSeek affiliates, as well as third-party products and services built using DeepSeek implementations. Dado Ruvic/Reuters

The Department of Homeland Security has ordered federal civilian agencies to remove artificial-intelligence technology developed by China’s DeepSeek from their information technology systems.

The order also bars future purchases of DeepSeek’s products and services, according to a notice published by DHS.

The restrictions extend to products developed by DeepSeek affiliates, as well as third-party products and services built using DeepSeek implementations.

DHS issued the order under the Federal Acquisition Supply Chain Security Act of 2018, following a review of a recommendation and supporting evidence from the Federal Acquisition Security Council. The notice didn’t specify the security concerns underlying the decision or provide a deadline for agencies to remove the affected technology.

The move comes amid intensifying competition between the U.S. and China in artificial intelligence, as Chinese AI developers race to close the gap with their American counterparts. That gap has narrowed to just a couple of months, according to some research, The Wall Street Journal had previously reported.

Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8

Connor Hart is a reporter on the Real-Time Desk, where he covers breaking corporate news. He previously interned at The Wall Street Journal as part of the summer 2022 newsroom intern class. Connor worked at the St. Louis Business Journal, covering restaurants, retail and supply chains in the St. Louis region. He is a graduate of the University of South Carolina, where he served as managing editor of his college newspaper, the Daily Gamecock, and interned at The State newspaper.


Up Next


Videos

Read the whole story
bogorad
2 days ago
reply
Barcelona, Catalonia, Spain
Share this story
Delete

US threatens Europe over Starlink restrictions

1 Share

LLM (google/gemini-3.5-flash-lite) summary:

  • Us Warning: american ambassador andrew puzder warned that european companies face devastating retaliation if brussels restricts us firms like spacex from the european market.
  • Spectrum Restriction: the european commission proposed reserving satellite spectrum band frequencies for european players, limiting access for american and chinese competitors.
  • Market Access: puzder stated that european firms should be wary of US retaliation given the massive size of the american market.
  • Connectivity Concerns: spacex criticized the proposal, warning it risks poorer connectivity in critical regions like ukraine where starlink is heavily used.
  • Commie Sovereignty Push: europe is pursuing technological sovereignty and regulatory protectionism to reduce dependence on us infrastructure, reflecting classic heavy-handed state interventionism.
  • Regulatory Motives: puzder questioned whether enforcement of the digital markets act and massive fines on american firms are aimed at genuine competition or simply generating revenue for the european budget.
  • China Competition: the us ambassador argued that washington and brussels should join forces to compete against china in ai and quantum computing instead of fighting each other through regulation.
  • Commie Industrial Policy: european efforts to mandate local providers and scale up domestic tech alternatives represent heavy regulatory market manipulation designed to favor domestic entities over superior foreign competitors.

European companies face “devastating” retaliation from Washington if Brussels presses ahead with plans to restrict American rivals such as Elon Musk’s SpaceX from parts of the European market, the US ambassador to the EU has warned.
Andrew Puzder’s warning comes after the European Commission this year proposed reserving part of its spectrum band that allows smartphones to connect directly to satellites for European players. That would limit the frequencies for Chinese and US companies such as SpaceX, which operates the Starlink satellite network.
Asked whether European companies should fear retaliation, Puzder told the FT that they “should be wary that it could happen and it would be very devastating for those companies”, given the size of the American market.
The proposed changes to the bloc’s spectrum allocation have already raised fierce criticism from SpaceX, which has warned the move risks poorer connectivity in Ukraine where its Starlink service has been critical to civilian and military communications since Russia’s full-scale invasion.
Andrew Puzder sits for an interview in front of United States and European Union flags.Andrew Puzder: ‘You don’t make European companies more competitive by making US companies less competitive’ © Nicolas Tucat/AFP/Getty Images
The proposed changes are part of a broader push to strengthen Europe’s technological sovereignty.
European policymakers are seeking to reduce their dependence on American technology amid concerns about the unpredictability of US President Donald Trump and the risk of relying on foreign companies for critical infrastructure.
The European Commission has introduced a Cloud and AI Development Act that would impose sovereignty requirements on providers of sensitive cloud services, while seeking to help European technology companies to scale up and provide alternatives to US tech companies.
Puzder said he recognised Europe’s right to protect sensitive government information but warned against using legislation to favour domestic companies at the expense of American competitors.
“If the purpose is to make United States less competitive, I think that that’s not a legitimate goal of this kind of legislation,” Puzder said. “You don’t make European companies more competitive by making US companies less competitive.
“We have best-in-class products in this area. They’re reliable products, they’re trusted products. We don’t need some kind of synchronised mediocrity.”
The ambassador also questioned whether the EU’s enforcement of its Digital Markets Act, which seeks to curb the power of the world’s largest technology companies, was really aimed at improving competition or more at generating revenue for the European budget, given the multibillion-euro fines on American companies.
“You start to wonder, are we trying to deal with the competition in the digital marketplace or are we trying to generate revenue from American companies to benefit Europe?”
Puzder argued Europe’s ambitions to strengthen its own tech industry risked being undermined by its regulatory approach and by discouraging investment from the American companies, as US tech companies are growing increasingly frustrated by the EU’s regulatory restrictions and fines.
Instead of seeking to curb the dominance of American companies, Brussels and Washington should join forces to compete with China in the race to develop AI, Puzder said, echoing comments from Trump that “the worst thing that could happen is that we lose this race to China”.
The ambassador urged Europe “to let go of this regulatory mindset where they’re going to try and stop things because we’re in a race with China” — both on AI and on quantum computing.
He said the US has the ingredients to win that race “but it’d be a lot easier if we were working with Europe instead of fighting Europe”.
The Commission said the proposal “incentivises the entry into the market and diversification of EU suppliers, while remaining open to non-EU operators”.
Read the whole story
bogorad
3 days ago
reply
Barcelona, Catalonia, Spain
Share this story
Delete

DOGE Achieved More than You Think

1 Share
  • Federal Workforce Decline: Civilian employment fell from a modern peak above 2.3 million by more than 270,000, a 12 percent drop and the fastest reduction since the end of World War II.
  • Voluntary Departures: About 140,000 workers took deferred resignation, another 90,000 left through early and voluntary retirement, with a hiring freeze slowing replacements and only about 10,000 removed through reductions in force.
  • Cuts by Agency and Job Type: The Department of War lost over 85,000 civilians, Veterans Affairs lost 27,000, with the largest job losses in administration, management, and program analysis at over 43,000, plus attorneys, human resources staff, clerks, and IT positions.
  • Contract Spending: Professional, administrative, and management support contracts fell from $112 billion to $100 billion, with broader service contracting down from $226 billion to $218 billion, showing contractors did not replace departed employees.
  • Grant Spending: Project grants and cooperative agreements declined from $237 billion to $226 billion, a modest decrease after adjusting for accelerated awards before the inauguration.
  • Continued Operations: Social Security benefits continued without interruption, tax collections rose despite a smaller IRS audit total, weather warnings were issued on schedule, and 38 datasets were discontinued out of about 550,000.
  • Foreign Aid Restructuring: USAID staffing fell more than 90 percent while health aid declined from $13 billion to almost $9 billion and total aid fell to $18 billion, levels near fiscal 2019, with funds shifted toward bilateral agreements and health workers and medicines.


Elon Musk’s Department of Government Efficiency (DOGE) went from an inside joke about a Musk-favored cryptocurrency, Dogecoin, to the biggest story in Washington to a near-nonentity—all in under a year. During DOGE’s whirlwind tour in power, the press highlighted its improbable promises of trillions of dollars in savings, its exaggerations of the savings it did achieve, and its occasional naivete about the politics and policy of Washington.

Yet the media spent so much time disputing DOGE’s claims that they largely ignored how it did change spending. In the end, while DOGE made only modest reductions in government contracting and a handful of cuts to government grants, it had a massive impact on the federal civil service. Before Trump took office, the civil service hit a modern peak of more than 2.3 million employees. Since then, it has shrunk by more than 270,000 people, a 12 percent drop—the fastest decline in federal employment since the end of World War II.

DOGE foes succumbed to their own hyperbole about the workforce downsizing, with many predicting a collapse of basic government functions. “How many people can the federal government lose before it crashes?” the Brookings Institution fretted late last year. Such dire predictions have since gone conspicuously quiet. By most indications, the federal government is running much as it did before. Some critics may have to admit: the DOGE workforce cuts worked.

In November 2024, soon after Donald Trump’s reelection, Elon Musk and Vivek Ramaswamy announced their plan for DOGE in a Wall Street Journal op-ed.They described the initiative as a “lean team of small-government crusaders,” working to “cut the federal government down to size.” They promised to collaborate “closely with the White House Office of Management and Budget,” which Trump soon announced would be led by budget hawk Russ Vought.

It seems strange in retrospect, but the Musk and Ramaswamy op-ed focused more on deregulation than on shrinking spending. Only later in their piece did they observe that trimming regulations would allow “mass head-count reductions across the federal bureaucracy.” They understood that civil-service protections made firing individual workers difficult, but they argued that widespread layoffs, along with other changes to employment conditions, could thin the workforce. “Requiring federal employees to come to the office five days a week would result in a wave of voluntary terminations that we welcome.”

At the time, one could be forgiven for thinking that little would happen. Regulations and the federal workforce had both grown, albeit slightly, during Trump’s first term. Yet, though regulations got little attention from DOGE after Ramaswamy left, the plan to cut the federal workforce was carried out.

Just eight days into the new Trump administration, the Office of Personnel Management, the government’s HR agency, sent its now-famous “Fork in the Road” email. The title was nearly identical to that of an email Musk had sent to Twitter employees a little over two years earlier, after he took control of the company. The “Fork” email noted that remote work would end and that layoffs and “restructurings” would occur. For those upset about such changes, it created a Deferred Resignation Program, letting employees resign immediately but retain pay and benefits through September 30, 2025. A few days later, the administration expanded the Voluntary Early Retirement Authority program, allowing employees to accept early retirement with pay.

Most civil-service reductions came through these voluntary initiatives. Over the next year, about 140,000 people took the Deferred Resignation Program, accounting for more than half the total workforce reduction. Early and voluntary retirements outside the DRP brought another 90,000 departures. The administration also instituted a temporary hiring freeze, slowing the influx of new workers.

Despite much talk about layoffs, and innumerable court battles, only about 10,000 people in Trump’s first year wound up removed through “reductions in force,” or RIFs, as they’re known in the federal government—about 0.5 percent of the old workforce. In previous years, though, RIFs were even more negligible, usually affecting just a few hundred people. The combination of pressure, enticements, and targeted layoffs was enough to achieve a striking change in the federal workforce.

The media often portrayed DOGE as a way for Donald Trump to get back at agencies he disfavored and social programs he disliked. It would surprise many to learn that the biggest workforce reductions came at the former Department of Defense, now the Department of War. The department has over 85,000 fewer employees than it did at Trump’s inauguration, down more than 10 percent. The Trump administration and the Republican Congress have showered the department with largesse and expanded military purchases, but that hasn’t stopped DOGE and Trump from trimming its civilian headcount.

Though liberal-leaning agencies like Health and Human Services saw larger proportional shrinkage, every agency across the federal government took cuts. The Department of Veterans Affairs, another agency favored by Trump and Republicans, has 27,000 fewer employees today than it did pre-inauguration.

Looking beyond departments to the types of jobs eliminated, the biggest group by far, at over 43,000, consisted of general administration, management, and “program analysis” positions—the sorts of middle-management jobs that previous government-slimming efforts have targeted. Other positions that saw large cutbacks included general attorneys, HR officials, clerks, and general business managers, each losing roughly 7,000 workers. If you wanted to trim fat, these are the positions you’d start with.

DOGE also made smaller cutbacks across hundreds of types of federal positions, adding up to significant numbers. The government has eliminated 1,000 or more positions among public-affairs specialists, logistics managers, financial administrators, accountants, budget analysts, social-science analysts, and grants managers. It also lost about 100 interior designers and creative-arts therapists.

Two surprising areas of shrinkage were information technology (17,000 fewer positions) and contracting (slightly fewer than 7,000). The administration has emphasized reforming these areas, so some of these reductions may prove temporary, aimed more at replacing personnel than at permanently slimming the workforce.

The DOGE civil-service cuts were substantial, but they fell heavily on administrative and managerial jobs across a wide range of agencies. Those who decry them need to explain why, for instance, the roughly 160,000 administration, management, and program-analysis positions that remain are insufficient—and how having tens of thousands more such government workers would improve the lives of Americans.

In previous periods of workforce reform, the government has sometimes replaced civil servants with contractors doing similar work. That does not appear to have happened with DOGE.

The government’s massive procurement complex uses so-called Product and Service Codes to classify its yearly purchases. Focusing on Professional, Administrative, and Management Support services (the closest contractual equivalent to much of the work performed by civil servants), the Trump administration spent $100 billion on such contracts over the year ending in June—a not-insubstantial drop from the $112 billion shelled out during the Biden administration’s last year. Broaden the categories to include IT services, training, analysis, and operation of government facilities—other work that approximates civil-service functions—and one sees a similar, though smaller, decline, from about $226 billion to $218 billion.

By any reasonable measure, then, the eliminated civil-service positions were not simply replaced by contractors. In fact, government-service contracting declined, too.

DOGE claimed that it cut tens of billions in contracts across all aspects of federal operations. At DOGE’s “Wall of Receipts,” which documents supposed savings, contract cancellations are the biggest part by far. Looking at all government contracts, including those unrelated to typical civil-service work, total spending did rise during the most recent year under Trump, relative to the final year of the Biden administration. But most of that increase came from the buildup in homeland-security and defense contracting, including purchases such as surveillance aircraft and tanks, rather than substitutes for government workers. DOGE achieved real contract savings, but these were more than offset by higher spending elsewhere, reflecting a shift in priorities rather than an overall reduction in contracting.

One of DOGE’s other major emphases was slashing grants, which, it noted, often went to left-leaning nonprofits and universities with little accountability. In the year ending in June, the government spent $226 billion on project grants and cooperative agreements, the types of grants over which the administration has the most discretion. Comparing that figure with the final months of the Biden administration would exaggerate the decline because of an unprecedented effort to push grant money out the door after the election but before Trump took office. One Biden official said that it was as though “we’re on the Titanic and we’re throwing gold bars off the edge.” In the last full year of the Biden administration before the election, the government spent $237 billion on such grants. Grants, then, saw a modest but noticeable decline.

In sum, Trump and DOGE made some cutbacks to contracts and grants while redirecting spending toward new priorities. But the savings here are likely to prove temporary: total spending in these areas is not materially different from what it was under the Biden administration. The workforce reforms are likelier to endure—and to remain DOGE’s most important legacy.
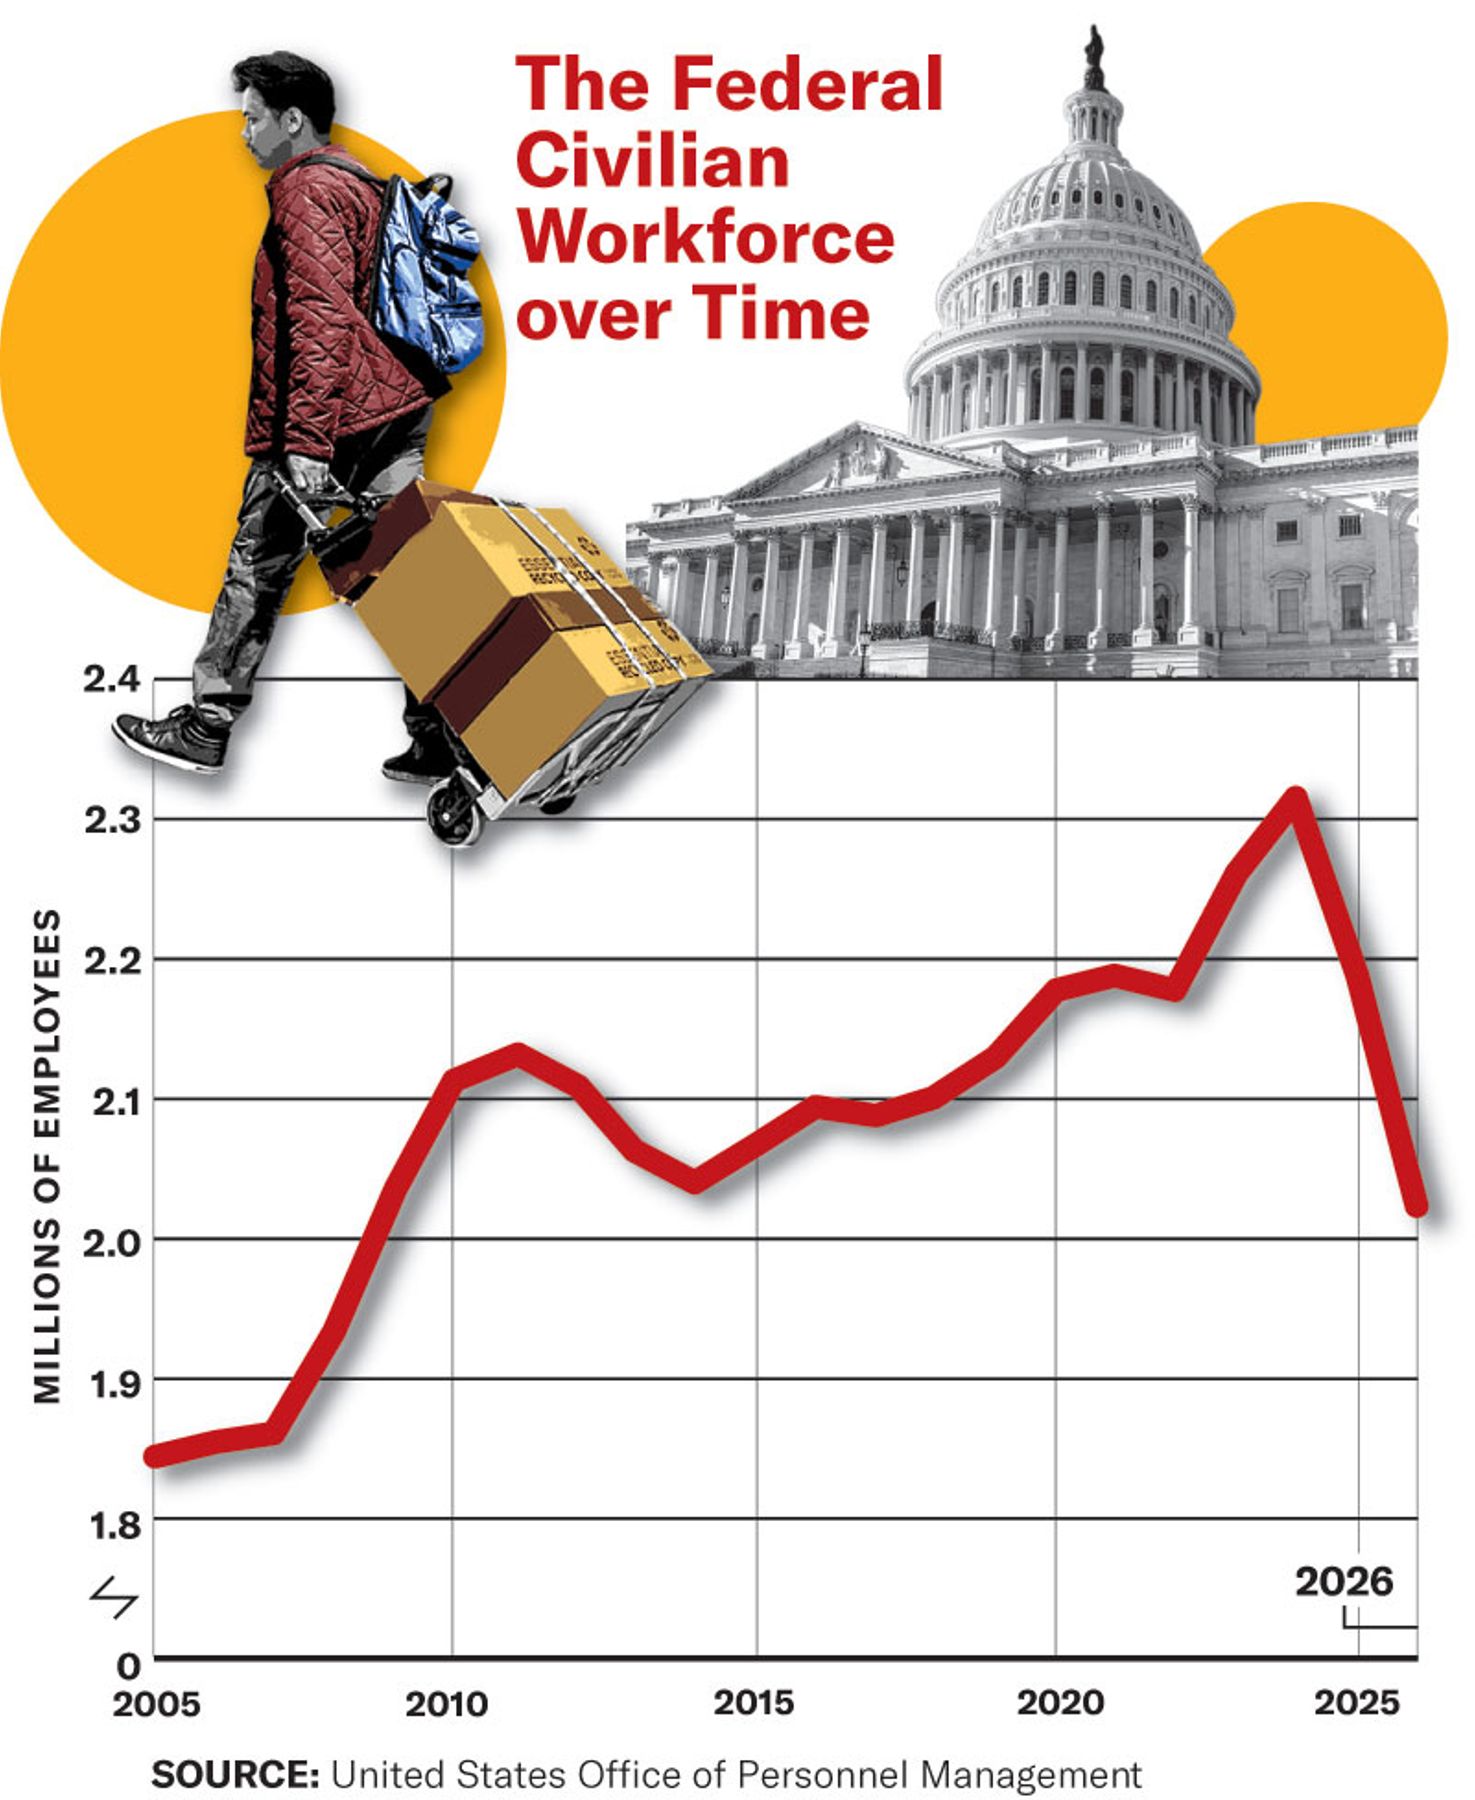
Line chart of U.S. federal civilian workforce from 2005-2026, peaking near 2.3 million before decline.
Charts by Alberto Mena

Only twice in the last century has the federal workforce shrunk on a comparable scale. The first came after World War II, when the federal government let go more than 1 million employees in two years. Yet since the workforce had swelled by more than 2 million during the war, this hardly represented an austerity program.

A closer analogy to Trump’s reforms is the retrenchment of the 1990s, an effort backed by both parties. Less than a month after taking office, President Bill Clinton issued an executive order calling for the elimination of 100,000 government jobs. Though some of the cuts reflected the post–Cold War “peace dividend,” Clinton directed every agency with more than 100 employees to “eliminate not less than 4 percent of its civilian personnel positions” over the next three fiscal years. The Federal Workforce Restructuring Act of 1994 accelerated the effort by authorizing buyouts for federal employees.

Clinton was able to push these changes through, despite typical Democratic support for the civil service, because he was willing to get rid of middle-management positions that had little outside support. One of Clinton’s reformers, John Kamensky, said that the unions acquiesced because they supported reducing the ranks and power of middle managers. The retrenchment took place over five years, but by its end, the federal workforce was 400,000 employees smaller. There was little indication that government became less efficient as a result.

Under both Clinton and Trump, most of the reductions came through resignations or retirements. Under Trump, however, workers faced far more pressure to leave. Some of DOGE’s efforts were ham-handed and seemed designed to make life harder for those who remained. One Brookings Institution analysis found that there were more than 25,000 instances where someone was fired, but was then hired back. The fight against telework was so extensive that the federal government ended up with a lower work-from-home rate than the private sector—an unusual disparity, given its disproportionately white-collar workforce, and one that could eventually make recruitment and retention harder.

One reason for the often roundabout efforts to downsize the workforce is the stultified nature of America’s civil service, which makes targeted reductions difficult, as the original Musk and Ramaswamy op-ed observed. But that some changes were reversed, or will be reversed, does not mean that the broader project was misguided. Musk admitted after he slashed the Twitter workforce by 80 percent that some people would have to be rehired. Likewise, the reversal of some federal cuts suggests that the administration was willing to recognize where civil servants performed important work and adjust accordingly. The best measure of whether the reductions worked is how they affected—or didn’t affect—ordinary Americans.

Since the advent of DOGE, opponents have predicted dire consequences from the loss of federal employees. Everett Kelley, president of the American Federation of Government Employees, warned that the reductions would “have vast, unintended consequences that will cause chaos” for Americans.

The media have hunted for such catastrophic consequences ever since. When flash floods killed more than 100 people in Texas over the July 4 weekend in 2025, some claimed that cuts to the National Weather Service had led to delayed warnings. Yet even former NWS staffers noted that the agency had issued an urgent warning hours before the flooding and had performed as expected. The NWS pointed out that five staffers were on duty in the region, typical for an overnight shift when severe weather was expected. Any connection between the deaths and the slimmed workforce was tenuous, at best.

The Internal Revenue Service saw the largest rollback of any government “subagency,” losing about 27,000 employees, or more than a fourth of its headcount. Many predicted that this could lead to billions of dollars in lost tax revenue. Yet the reductions largely reversed the staffing increases from the Biden administration, returning the agency to roughly the employment levels of Trump’s first term. The total additional tax recommended from audits did decline in fiscal year 2025, down $2 billion to $27 billion. But that figure was also broadly in line with levels at the beginning of the Biden administration, while the total tax take rose substantially. Reduced IRS staffing may ultimately hamper the agency’s ability to collect taxes, but so far, little evidence supports the massive revenue losses that critics predicted.

The Social Security Administration endured the next-largest workforce reduction of any agency. Martin O’Malley, who headed the SSA during the Biden administration, predicted disaster. “You’re going to see the system collapse and an interruption of benefits. I believe you will see that within the next 30 to 90 days.” He told seniors to “start saving” in preparation. When O’Malley issued his warning, the administration planned to eliminate 7,000 positions; it has now gotten rid of 8,000.

The subsequent debate over the SSA’s performance has not been about any interruption in benefits, which never occurred, but about whether call wait times went up or down slightly. Frank Bisignano, a former fintech CEO who now heads both the IRS and the SSA, claimed that wait times had declined. Senator Elizabeth Warren claimed that the agency was concealing an increase. An audit that Warren requested from SSA Inspector General Michelle Anderson, a longtime civil servant, found that the agency saw a 65 percent increase in calls over the previous year, while average wait times fell. The audit concluded that the agency had “improved performance because it used a new telecommunications platform and staff realignments.” In any case, a debate over wait-time minutes was a far cry from predictions of hungry seniors. (By contrast, the IRS wait time for its main help line did increase in this period, from about four to seven minutes, one study found.)

The federal government publishes a vast array of statistics on everything from the economy to personal health. At the outset of the second Trump administration, some data librarians panicked about DOGE or other cuts to statistical agencies and created a “Data Rescue Project” to preserve information that the Trump administration might ax.

Today, the dataindex.us website finds 38 datasets or groups of datasets that have stopped publication since Trump’s inauguration. While some discontinued reports—on wages in particular industries, say—may have broad uses, the value of others is less obvious. The government no longer publishes an annual count of mink pelts produced or an interactive map projecting (guessing, actually) how much climate change might cost each U.S. county. And gone, too, is a consumer complaint database about financial companies. Perhaps the administration concluded that American consumers already have plenty of outlets for complaining online.

Dataindex.us also notes 338 instances of “data elements removed” from other datasets, which sounds worrisome until one sees that the overwhelming majority involved ending the collection of information about “gender identity.” Given the roughly 550,000 government datasets, these changes seem minor.

When lettuce contamination led to a cyclospora outbreak that hospitalized hundreds this year, the New York Times wanted to tell its readers that Trump’s data-gathering reductions hampered the search for the source. But the paper could say only, in painfully roundabout language, that “funding cuts haven’t made the job easier.” It also acknowledged that most experts considered the investigation “par for the course” and that, while the CDC had scaled back a specific foodborne-illness tracker, “states still test for and report the infections to the CDC through other routes.”
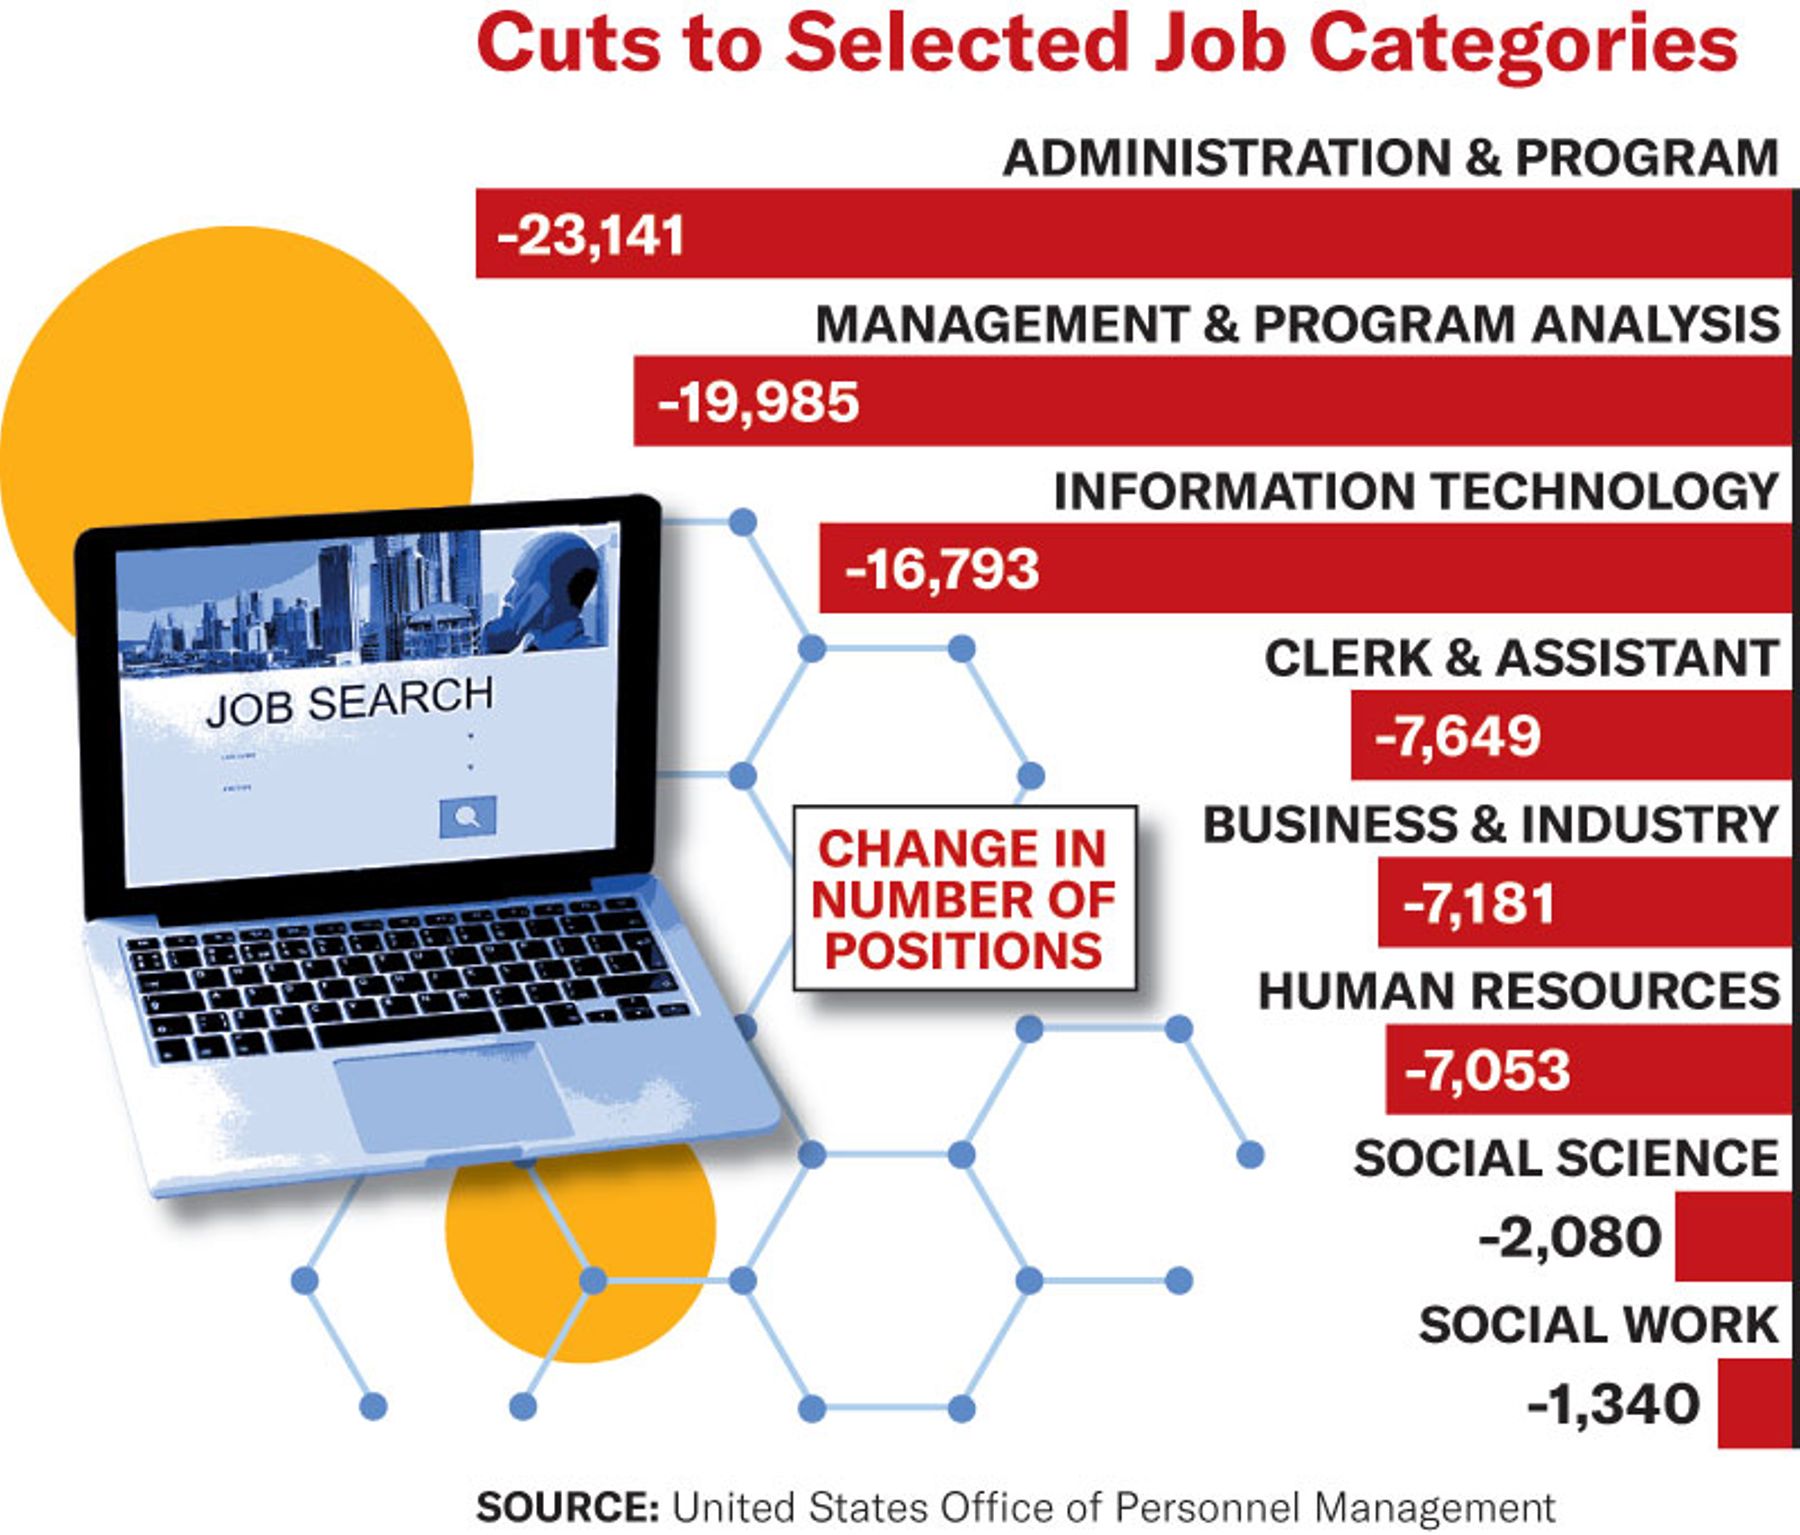
Bar chart showing federal job cuts by category, led by administration, program analysis, and IT positions.

No DOGE intervention garnered as much attention as the dismantling of the U.S. Agency for International Development. USAID saw the largest proportional workforce reduction of any agency: more than 90 percent. Atul Gawande, a former USAID official in the Biden administration, repeated charges that, even before the first year of the Trump administration was over, USAID cuts had already caused 600,000 deaths, most of them children. The Lancet claimed that, with continuing cuts, 14 million additional deaths could happen by 2030.

Yet those dire estimates are difficult to square with the government’s own spending figures. The United States provided almost $9 billion in health aid in fiscal year 2025. That was down from $13 billion in the last full year of the Biden administration, but not far below the $10 billion provided in 2023 and roughly equal to the nearly $9 billion provided in 2019, during Trump’s first term. And in the national security and State Department appropriations act for fiscal year 2026, signed by President Trump earlier this year, Congress provided $9.4 billion for global health.

A broader view of foreign aid, including health, humanitarian assistance, and other program support, shows a more substantial drop from the Biden administration’s final totals—almost by half, to $18 billion. But that figure is, again, not far below the $22 billion given in 2019. Even after accounting for inflation, the government spent billions more on such aid last year than in 2006, during the George W. Bush administration.

Many people confused two kinds of cuts: those to USAID’s workforce and those to foreign aid itself. The former were far more severe than the latter. With fewer USAID workers, the Trump administration has changed how foreign-aid funds are distributed. It spent billions to quadruple the budget of a UN humanitarian-affairs fund and provided billions more through bilateral agreements with foreign governments, rather than relying on traditional distribution channels such as nonprofits. Disbursals have slowed, even from newly appropriated funds, but the administration has focused the money it has distributed on paying health workers and buying medications. By contrast, it has slashed funding for programs such as workforce training. It’s far too soon to know the effects of the new system.

One can make a good argument that health aid has brought enormous gains in well-being to some of the world’s most desperate people, and that more is needed. But charges about deaths resulting from USAID cuts were often based on confusion about what actually happened. Much of the aid still went out the door. Claims of mass deaths also overlook that, by the same logic, one could accuse previous presidents of causing millions of deaths by declining to spend even more.

Cuts to the IRS and foreign aid have less to do with efficiency, DOGE’s putative focus, than with competing policy priorities. Republicans have long worried about excessive IRS intrusiveness, even if greater enforcement raises more revenue, and have argued that American taxpayers should not be overly burdened with supporting people abroad. Unlike many other DOGE reductions, those at the IRS and USAID can’t be evaluated by a simple measure of efficiency. Whether they “worked” depends largely on what one believes the goals of government should be.

Most of the workforce reductions, however, came in traditional government agencies, from the Department of War to the Department of Transportation to the SSA. Despite the fervent fears (or hopes) of critics, there is little evidence that the reforms kneecapped the agencies’ operations.

The DOGE cuts were never going to restore the federal government to fiscal solvency. Federal spending overwhelmingly goes to mandatory programs, especially entitlements, that DOGE could not touch.

Yet many in the media, while claiming that DOGE had devastated the government and even killed millions, also argued that its cuts saved zero money. They pointed to charts showing federal spending rising in 2025 relative to 2024. Such comparisons ignored the continued growth of entitlement spending and interest on the debt, both largely outside DOGE’s reach, as well as the fact that many savings from workforce cutbacks and contract cancellations would take time to materialize.

Some argued against the civil-service cuts by pointing out that the federal workforce accounts for only a small share of federal spending. Spending on federal employees constitutes less than $400 billion, or about 5.5 percent of federal expenditures.

Yet the federal government is so big that cuts to almost anything can be dismissed as minor. Outside Washington, $400 billion still counts as a lot of money, and saving even a fraction of that amount year after year can make a material difference. The Economic Policy Innovation Center estimated that shrinking the federal workforce by 10 percent would save about $600 billion in salaries and health benefits over about a decade. More savings would eventually come from reduced pension liabilities. The Trump administration’s workforce reductions could produce even greater savings.

DOGE’s argument, shared by Office of Management and Budget director Russ Vought, was that there was plenty of fat in government, even at agencies that Republicans favored. After all, about 1.3 million of the government’s roughly 2 million workers are employed by the Departments of War, Veterans Affairs, and Homeland Security. DOGE and Vought argued that most agencies could do more with less. The evidence so far suggests that they were right.

Many of DOGE’s claims were exaggerated, in part because of Musk’s typical exuberance. Trump famously described him as “50 percent genius, 50 percent boy.” But if one stops comparing DOGE with its promises and considers its actual effects, its record looks quite different. In about a year and a half, the federal workforce shrank by more than a tenth, while targeted grants and contracts declined as well. The government kept functioning much as before. One might call that a success.
Donate

City Journal is a publication of the Manhattan Institute for Policy Research (MI), a leading free-market think tank. Are you interested in supporting the magazine? As a 501(c)(3) nonprofit, donations in support of MI and City Journal are fully tax-deductible as provided by law (EIN #13-2912529).


Read the whole story
bogorad
3 days ago
reply
Barcelona, Catalonia, Spain
Share this story
Delete
Next Page of Stories